Digital technology is transforming the financial industry, displacing traditional transaction models. According to forecasts, the global fintech market will grow by 15.8% annually through 2033, reaching a valuation of more than $800 billion. At the same time, the rapid development of financial technology comes hand in hand with the need for regulation and licensing. Without an experienced partner — legal or regulatory — these challenges can slow a companyʼs growth or even block its entry into a market.
End-to-end support for fintech projects at every stage — from choosing a jurisdiction to obtaining a license — is provided by International Fintech Business (IFB). The company works with a range of license types: banking, payment, cryptocurrency, brokerage, and investment. In an interview with Forbes BrandVoice, Vladyslav Zaporozhchenko, co-owner of IFB, spoke about how the companyʼs services help fintech startups overcome regulatory barriers and enter global markets.
Company Profile
International Fintech Business is an international consulting company founded in 2022 through the merger of Qiuntex and Pearly Mount Consultants. It provides legal consulting on financial licensing (banks, EMI/SEMI, API/PI, SPI), support in sourcing and selling ready-made financial institutions, integration with payment systems (Visa, Mastercard, SWIFT, SEPA), and the implementation of software for online banking and mobile applications.
Today, IFB operates in 103 countries. The company works with clients across multiple jurisdictions, including EU countries, the U.S., Canada, as well as regions of Asia and Africa. In 2025, IFB opened a representative office in Japan, allowing it to license European businesses for Asian markets. IFB was founded by Vladyslav Zaporozhchenko and Yuliia Raubishko.
Key Services
What requests do Ukrainian fintech companies most often come to you with?
We specialize in comprehensive legal support for companies seeking to enter the financial markets of Europe, the UK, Hong Kong, South Africa, Australia, Canada, the U.S., and Japan. Our services include advising on licensing our clientsʼ financial activities, structuring share capital, guiding companies through compliance procedures and regulatory requirements, and preparing and filing applications with regulators in any of the 103 countries we work with.
We also handle integration with international payment systems such as Visa, Mastercard, and UnionPay, help clients open segregated and correspondent accounts, and provide the option to obtain principal membership — the status of a direct participant in an international payment system. If direct membership is not feasible, we can arrange BIN sponsorship through third-party providers, allowing a company to issue payment cards and process financial transactions without becoming a direct member of the payment system.
Another area worth highlighting is the sale of ready-licensed financial institutions. We maintain a database of banks, payment institutions, and other financial companies that are already operating in the market and are looking for investors or buyers.
So, one can come to you and simply buy a ready-made license?
We only provide legal consulting and support in executing such deals — that is, we help structure agreements between the buyer and seller of a company. For example, for a seller, we provide legal consulting and list information on our platform to help find an investor or buyer. During the process, we conduct a company valuation, help set the sale price, and carry out a compliance check.
Types of Licenses and the Conditions for Obtaining Them
What types of international licenses are there? How do they differ?
The main question we ask a client is what types of operations they plan to conduct, as this determines the most suitable license and jurisdiction. The key differences are in turnover limits and capital requirements. Licenses with turnover limits allow a financial institution to operate up to a specified threshold — typically between €15 million and €36 million per year.
The simplest of these is the Small Payment Institution (SPI). In some countries, it doesnʼt require substantial share capital, but it comes with clear restrictions. In Poland, for example, the monthly limit is €1.5 million, and a single transaction is capped at €1,000. The next tier is the Payment Institution (PI), which requires €125,000 in capital and allows for larger turnover and broader functionality.
Unrestricted licenses require more capital — for example, obtaining a full Electronic Money Institution (EMI) license requires founding capital of €350,000, while a Small Bank license requires €2 million. Itʼs worth noting that capital requirements can be more lenient in certain jurisdictions. For instance, the Money Service Business (MSB) license in Canada and the U.S., as well as the Money Service Operator (MSO) license in Hong Kong, donʼt carry mandatory share capital requirements, which makes them attractive to early-stage startups.
What key conditions must be met to obtain an international financial license?
When a company seeks a financial license, the international regulator checks three main factors (though not only these).
First, the source of a shareholderʼs capital — full proof of the legality of the funds and payment of taxes is required. Even crypto capital must be legalized. For «high-risk» clients, regulators may require an increase in share capital.
The second factor is the reputation and track record of the shareholder and team. The regulator reviews the CVs and work experience of key individuals, checking for negative information and sanctions lists. Even old negative publications or complaints online can delay the process or lead to a refusal.
The last factor is the reliability of the IT infrastructure. This is often the most difficult part of the review. Itʼs critical to choose an experienced provider with a proven track record of integrating with major payment systems such as SWIFT, Visa, and Mastercard. Our success rate over the past three years stands at 94%. The secret lies in pre-assessment — we spend four to five weeks auditing a clientʼs readiness before filing documents, which saves months of time and tens of thousands of euros.
In addition, as a forward-looking company, IFB is already deploying artificial intelligence for client pre-audits and data verification, which significantly speeds up the due diligence process and improves the quality of analysis.
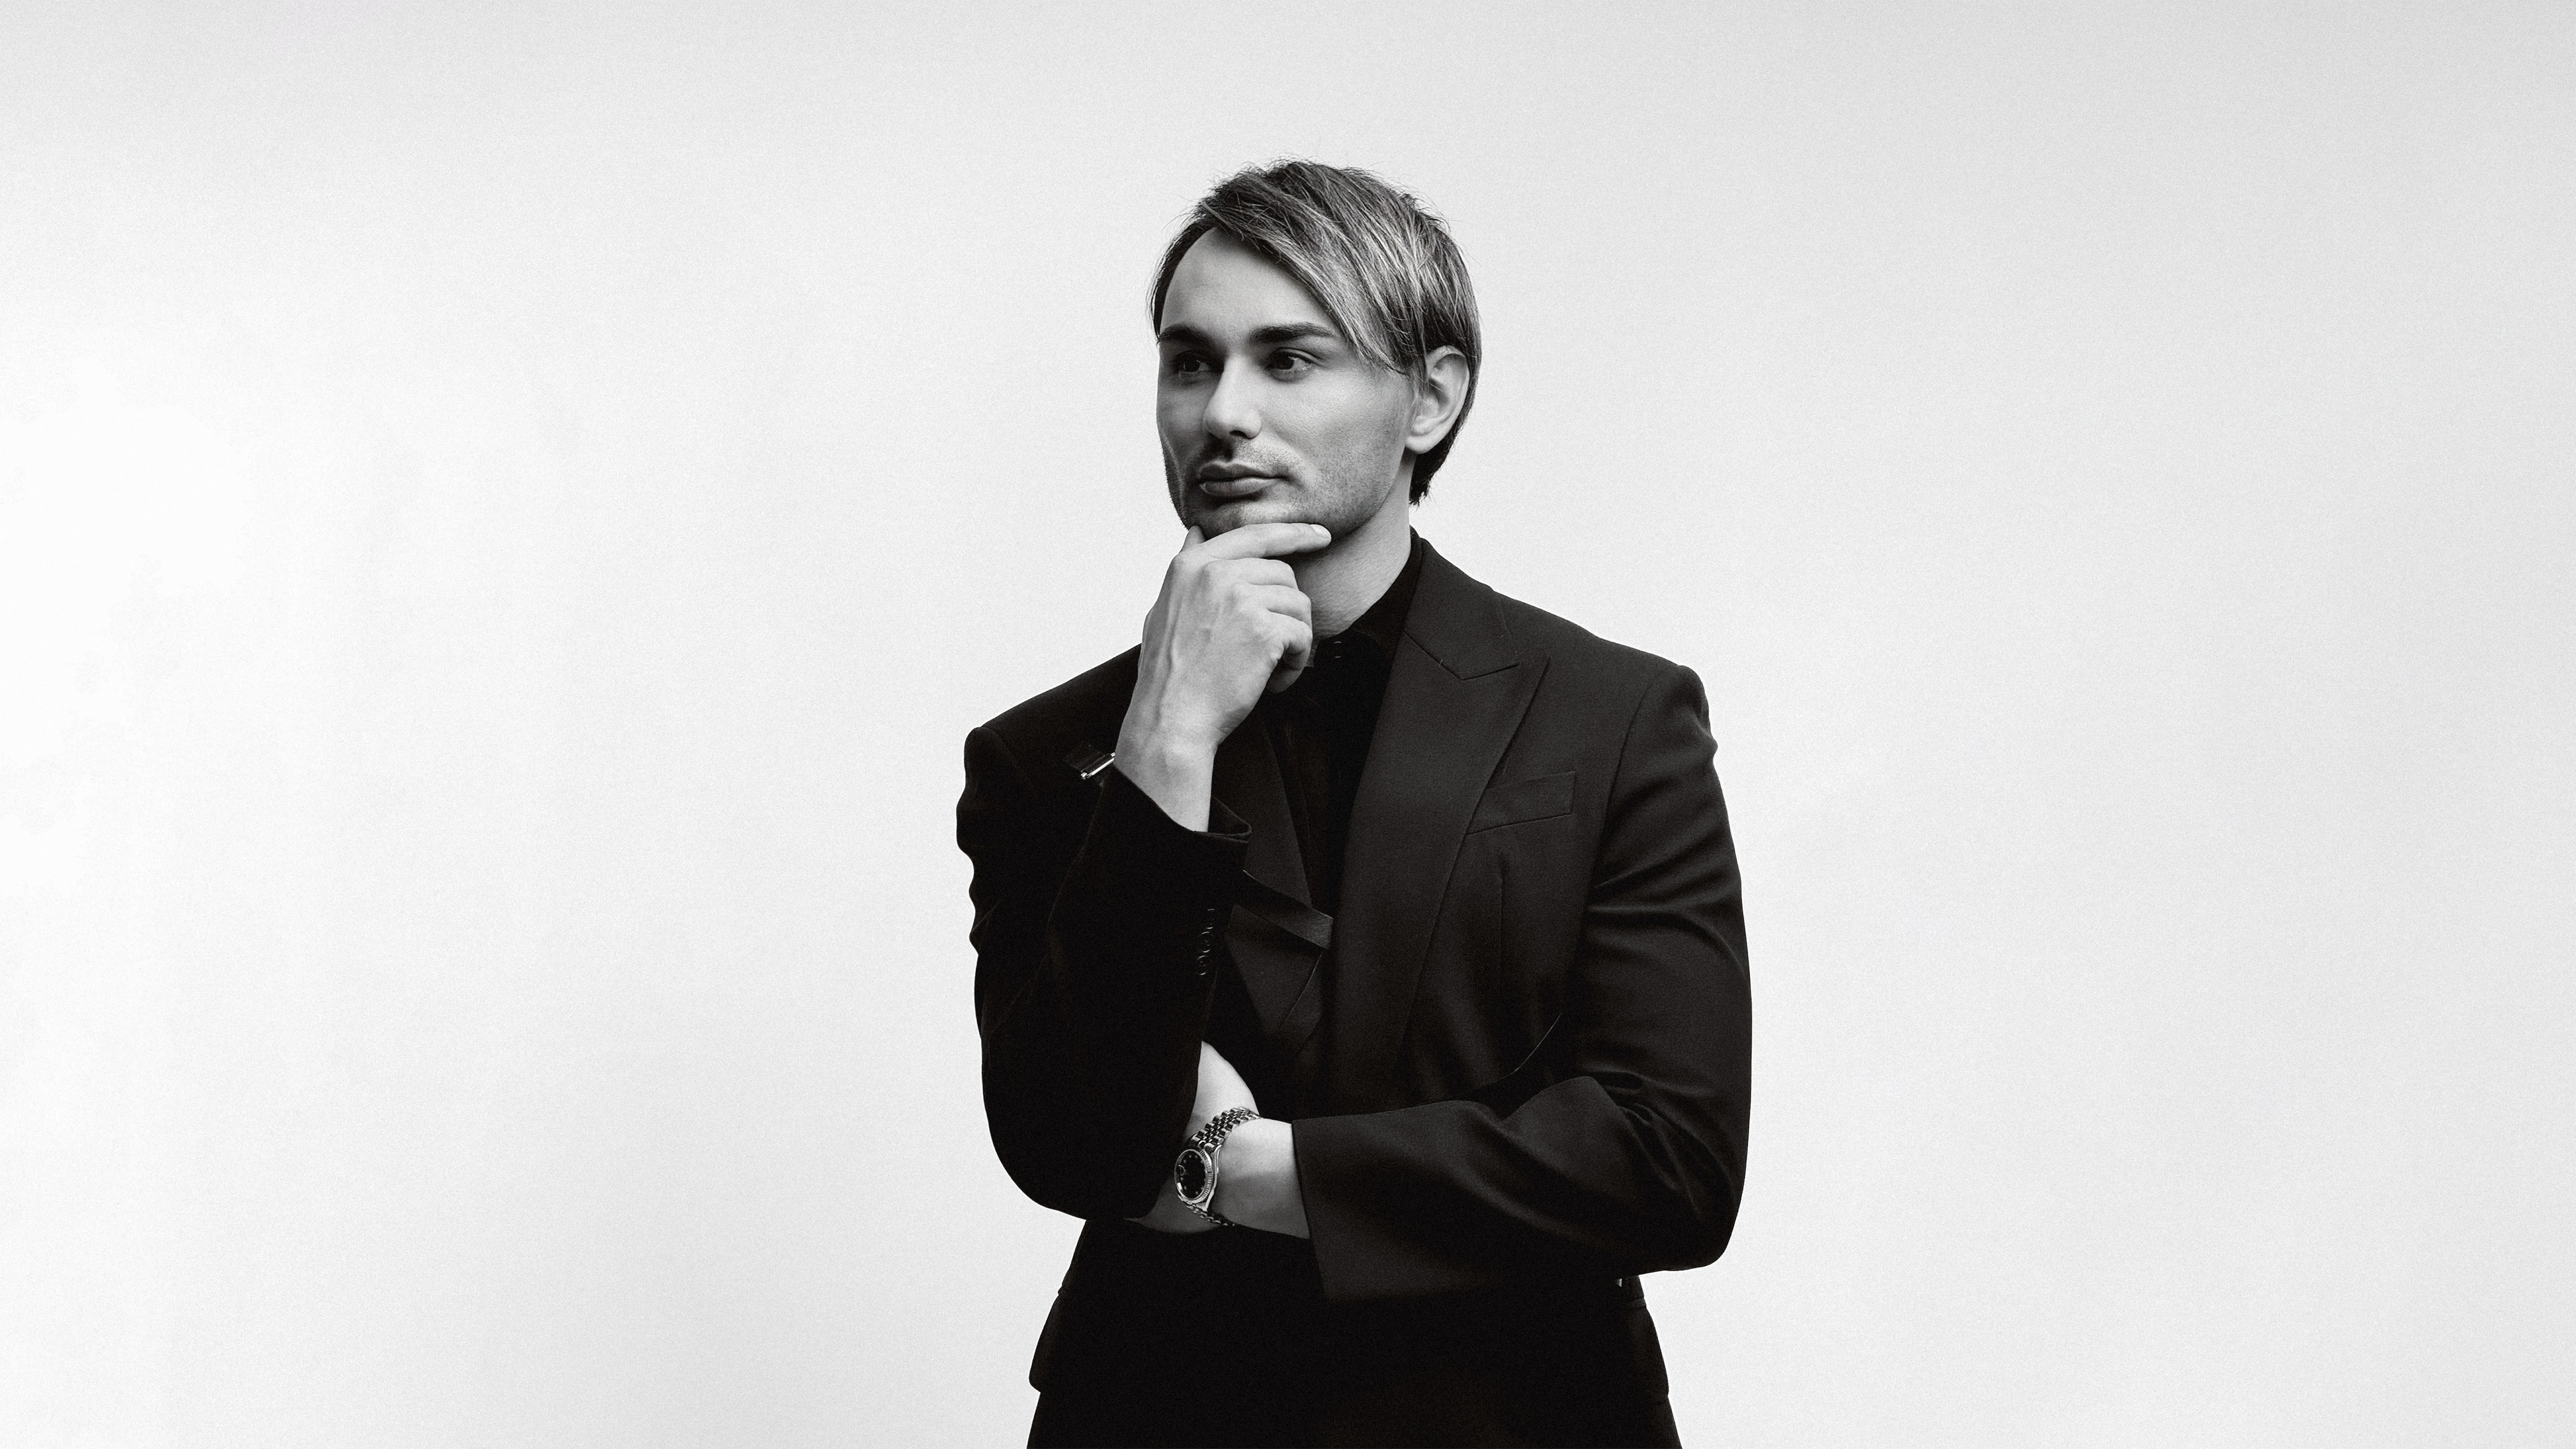
Vladyslav Zaporozhchenko, co-owner of IFB
Which European jurisdictions are the most attractive for obtaining licenses?
It all depends on the type of license. Today, for example, the Netherlands is the leader in obtaining EMI licenses — last year, two of our six applications there were approved. Lithuania comes second, though its central bank is currently overloaded following the UKʼs exit from the EU, so we donʼt recommend it. Latvia, on the other hand, is taking an active stance: the country has openly declared its readiness to welcome new investors and has ambitions to become the Balticsʼ new fintech hub.
Other recommended countries include Spain, Portugal, and France. Poland mostly issues SPI licenses, but its regulator frequently revokes them for failure to meet requirements.
How much do your licensing support services cost? How long does the process take?
The cost of our services varies greatly depending on the type of license and jurisdiction. For example, a Money Service Business (MSB) license in Canada costs €15,000, while an EMI license with a pre-audit of shareholders and the core team costs €120,000, with timelines ranging from eight months in the Netherlands to up to 18 months in Lithuania and the UK. Itʼs important to understand that timelines depend not only on us but also on how prepared the clientʼs team is.
Itʼs not uncommon for the first consultation to reveal that a clientʼs budget doesnʼt match the capital requirements for the license they want — an EMI, for example.
According to our statistics, 73% of fintech startups underestimate their licensing budget by 1.5 to 2 times. Thatʼs why we always start with an analysis of the budget and the planned types of operations: whether itʼs money transfers, acquiring, investment activity, or active fund management. This approach allows us to select the most realistic and effective licensing strategy for each business.
The Path to European Standards
Whatʼs the difference between fintech in Ukraine and in Europe?
Ukrainian and European payment systems differ in functionality and regulation. Ukrainian payment systems licensed to transfer funds are limited to basic operations. They have no regulatory framework for direct connection to international systems such as Visa or Mastercard; thatʼs only possible through a partner bank. In addition, unlike their European counterparts, segregated client accounts in Ukraine arenʼt covered by the Deposit Guarantee Fund. In Europe, similar accounts are protected by law: client funds are ring-fenced from the companyʼs own assets, and oversight mechanisms ensure their safety even in crisis situations.
European payment systems also offer broader functionality. For example, this includes the ability to hold a multi-currency account (supporting more than 30 currencies), card issuance and processing that enables companies to issue Visa/Mastercard cards, carry out SWIFT and SEPA transfers, process payments, as well as access to international settlements and the ability to open correspondent accounts.
European payment systems also have more advanced client verification procedures, including biometric verification via video and photo ID, which allow users to be identified remotely, quickly, and securely, simplifying the onboarding of new clients.
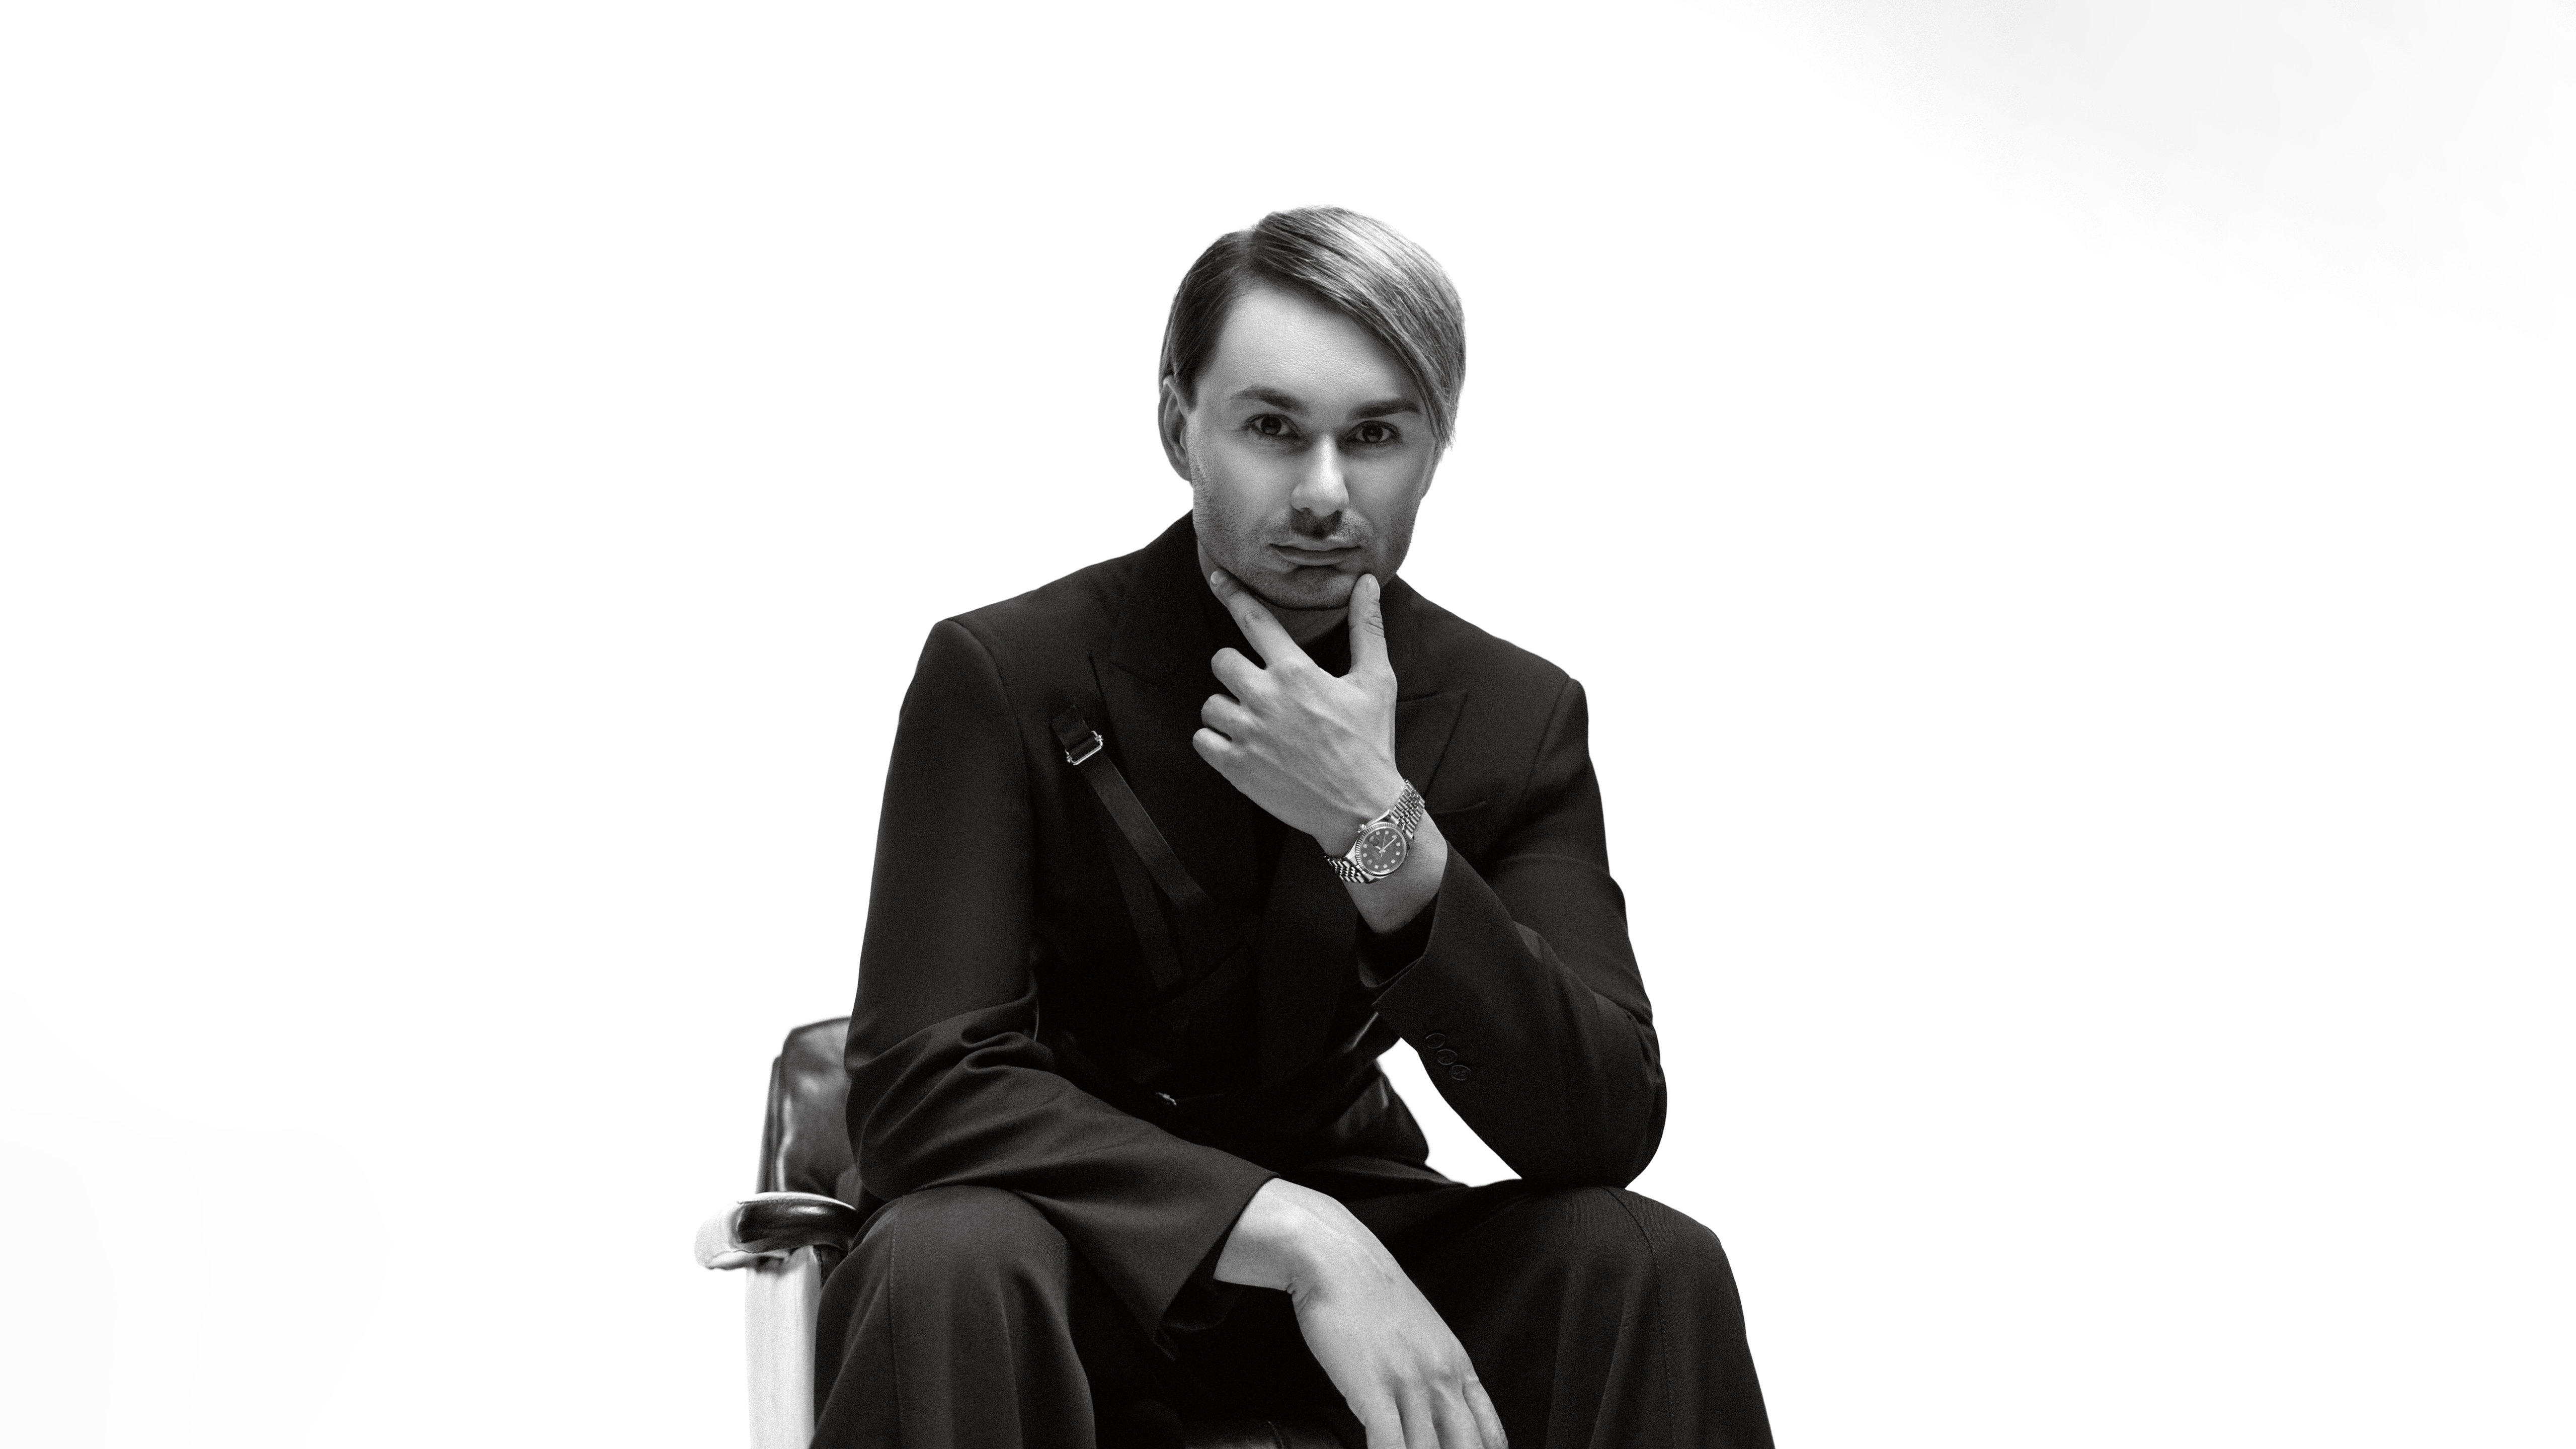
Vladyslav Zaporozhchenko, co-owner of IFB
What steps do you think the National Bank of Ukraine should take to develop the financial sector?
The National Bank of Ukraine and the Verkhovna Radaʼs banking committees should form a working group and begin implementing European legislation into Ukrainian law. But most importantly, licensing authority should be transferred from the NBU to an independent commission. The experience of developed countries shows that such an independent commission fosters the rapid development of the payment fintech business and the emergence of neobanks, small banks, and payment institutions with lower capital requirements.
Whatʼs the state of cryptocurrency regulation in Ukraine and Europe?
Until 2025, Europe had no unified approach to regulating crypto assets, but the situation changed dramatically after the European Parliament passed the MiCA (Markets in Crypto-Assets) law. The law requires full licensing: having share capital, appointing an AML officer, and implementing internal policies and procedures. In effect, the market has become fully regulated. As a result, this year weʼve received more than 100 requests from companies looking to relicense from VASP to CASP status in order to comply with the new rules.
In Ukraine, regulation of this market remains on hold. Even before the full-scale war, there was a fierce fight between regulators — the National Bank and the National Securities and Stock Market Commission — over the right to regulate the crypto market. The result was a law that included no mechanism for an economic amnesty for crypto assets, which eliminated any real possibility of legalizing and integrating them into the Ukrainian economy. The law was vetoed by the president and remains stuck over tax-related amendments.
How do you see the future of the financial sectorʼs development in Ukraine and globally?
Ukraine needs to adopt Europeʼs experience faster — implementing its clearing systems. The world is undergoing a global transformation: the aging SWIFT system is no longer synonymous with fast payments, since transfers through it take one to three days and come at a high cost. The future instead belongs to virtual and quasi-currencies built on blockchain technology, which allow instant transfers within seconds. Itʼs no surprise that even SWIFT and the worldʼs leading banks are actively developing their own blockchain systems.
Alongside blockchain, the financial sector is undergoing an artificial intelligence revolution. The worldʼs leading banks — from JPMorgan to HSBC — are already using AI to automate credit decisions, detect fraud, and manage risk. Goldman Sachs applies machine learning algorithms to trading, while Bank of America serves millions of clients through its AI assistant, Erica. Regulators are adapting too: the European Central Bank is developing AI systems to supervise financial institutions in real time.
Our company isnʼt lagging behind either — weʼre actively using AI-based solutions, and weʼre excited to announce that starting July 1, our clients will have access to an AI-powered Telegram chatbot, where theyʼll be able to get direct information about companies listed for sale in various jurisdictions, as well as instant answers to basic questions about licensing and regulatory requirements.